Veterans & Military Families
How does a VA home loan work when buying in Bend or Central Oregon?
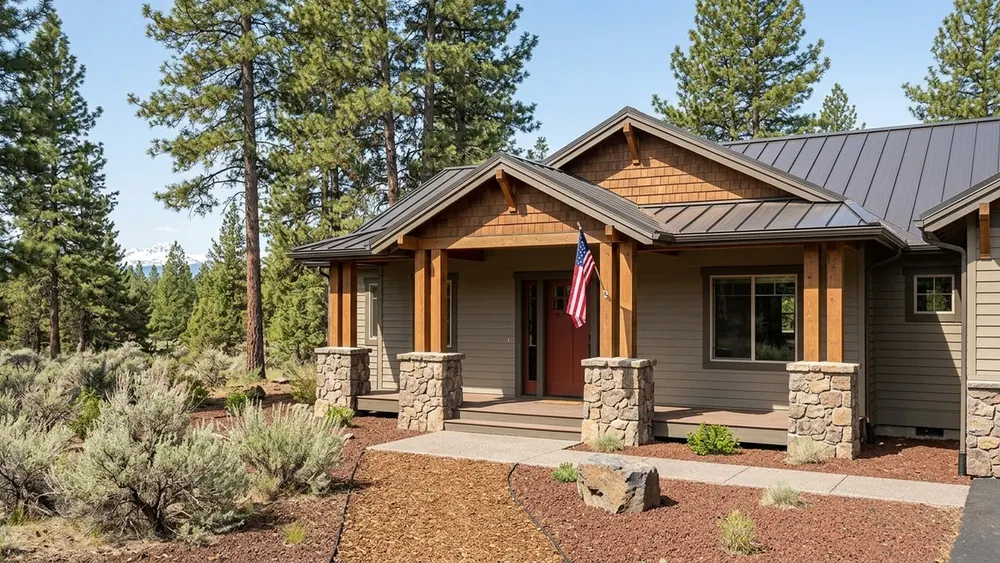
Buying with a VA home loan in Bend or Central Oregon follows the usual buying steps, with a few added ones: confirming eligibility first, working with a lender that offers VA loans, and a VA appraisal alongside your own inspection.
On this page
The short answer on VA home loans
A VA home loan is a mortgage backed by the VA, the U.S. Department of Veterans Affairs, and offered through private lenders. Buying with one in Bend, Sunriver or elsewhere in Central Oregon follows the same basic path as any purchase: find a home, make an offer, inspect, and close. The difference is a few added steps along the way, such as confirming eligibility before you start and a VA appraisal of the home before the loan can be approved.
Knowing those steps in advance matters because each one has an owner. Some questions belong to you, some to the real estate side of the purchase, and many belong to the lender or the VA. When you know who answers what, the process feels far less mysterious. You spend less time wondering whether something is a problem and more time asking the right person, which tends to keep the purchase moving calmly from one step to the next.
This article is educational. It explains the general shape of buying with a VA home loan and who confirms each part. It does not state eligibility rules, loan terms, costs or requirements, because those depend on your service history, your situation and the program rules in effect when you buy. Treat every program detail as something to confirm with a VA-approved lender or the VA before you rely on it, and expect the details to differ from one buyer to the next. Asking early, before you fall for a particular home, gives you room to understand the answers.
Confirm your eligibility before you search
The first step happens before you look at a single home. Ask a VA-approved lender to help you confirm whether you are eligible for a VA home loan and how much of your benefit may be available to use. A lender can usually help you request a certificate of eligibility, the document that shows the VA has recognized your eligibility. Questions about entitlement, a previous VA loan, or a surviving spouse’s eligibility go to the lender or the VA.
- Ask a VA-approved lender whether you are eligible and how to request a certificate of eligibility
- Confirm with a VA-approved lender how any earlier VA loan affects the benefit available now
- Ask the lender whether a funding fee applies to you and how it would be handled
- Confirm with the VA or the lender what occupancy expectations come with the loan
Choose a lender that offers VA loans
Not every lender offers VA home loans, and those that do can differ in how they work with buyers. It is worth talking with more than one lender that offers VA loans and comparing how each explains the process, the costs and the steps ahead. A pre-approval from a lender gives you a clearer picture of your budget before you start touring homes in Bend, Sunriver, Redmond or anywhere else you are considering.
- Ask each lender how often they work with VA home loans and what they need from you
- Ask what costs to expect at closing and which ones the loan may or may not cover
- Ask how the VA appraisal is ordered and what happens if it raises a condition question
- Ask the lender how its own steps usually unfold, so you can plan your move around them
- Ask which documents to gather now so the approval does not stall later in the purchase
How an offer and contract proceed
Once you find a home, the offer works much like any other purchase offer. It names a price, the terms you are asking for, and the conditions the purchase depends on, such as financing, an appraisal and an inspection. Your offer makes clear you are using a VA home loan. Helen can walk you through how an offer is put together on the real estate side and the order in which documents usually come up after it is accepted.
Some buyers wonder whether a VA home loan changes how a seller sees an offer. The honest answer is that every seller weighs offers differently, and no one can predict how a particular seller will respond. A clear pre-approval and a well-organized offer help any buyer present a steady picture. Questions about which costs can be negotiated between buyer and seller under a VA home loan belong with your lender, and the legal meaning of any contract term belongs with a real estate attorney.
After an offer is accepted, the purchase moves into a period where several things happen at once: the lender works on the loan, the appraisal is ordered, and you arrange your own inspection. Keep a simple list of who is handling each item and what they need from you. When something new comes up, add it to the list with the name of the person who will answer it, so nothing sits unanswered while you wait. A shared list also makes it easier to see when a step is finished and what comes next.
The VA appraisal and your own inspection
A VA home loan includes a VA appraisal, ordered through the lender. It looks at the home’s value and may also raise questions about the home’s condition. If the appraisal notes a condition item, ask the lender what it means for the loan and what options are available. Do not assume what the outcome will be; the lender and the VA are the ones who confirm what an appraisal requires and how any item can be addressed.
An appraisal is not the same as a home inspection, and it is not a substitute for one. A licensed home inspector looks at the home on your behalf, at its systems, structure and condition, so you understand what you are buying and can ask questions while there is still time to act on the answers. Even when an appraisal goes smoothly, an inspection is still worth considering. Questions about services, permits or property records go to the City of Bend for a home inside Bend, or to Deschutes County outside city limits.
I want you to know who answers each question before you need the answer. Confirm the loan details with a VA-approved lender, and still have the home inspected for your own peace of mind.
From loan approval to closing
Closing is the final step, when the loan is funded, documents are signed and the home becomes yours. Before then, the lender will confirm that its conditions are met, including anything that came up during the appraisal. Ask the lender early what final documents they will need and when, and ask how you will know what amount to bring to closing. Keeping in steady touch with the lender is the simplest way to avoid surprises at the end.
A move often has its own moving parts, especially for a military family with orders or a veteran starting a new chapter. Questions about how your timing, your orders or a move from another state affect the loan go to the lender and, where relevant, to your installation or relocation office. Helen can help you line up the real estate steps around the dates you already know, while those offices confirm the parts that belong to them.
What to gather before talking it through
Before a first conversation about buying, write down a few things: whether you have confirmed eligibility yet, which lenders you have spoken with, the kind of home you are looking for, and any dates that shape your move. Note the questions you have not been able to answer. The same preparation works whether you are looking in Bend or Sunriver or widening the search to La Pine, Redmond or Sisters.
Then point each open question at the right source. Eligibility, entitlement, the certificate of eligibility, any funding fee, appraisal questions, occupancy and loan limits all go to a VA-approved lender or the VA. Condition goes to a licensed home inspector, contracts to a real estate attorney, insurance to an insurance agent, and local services to the city or county. With each question in the right place, the purchase becomes a series of clear, manageable steps.
If you would like to talk it through, you are welcome to bring your notes to Helen Marston, an Oregon licensed real estate broker with Keller Williams Realty Central Oregon. You do not need a lender chosen or a home in mind, and a first conversation can happen in English or Chinese. Which part of buying with a VA home loan feels least clear to you right now: eligibility, the lender, the appraisal or the offer?
This article is general information about buying, selling and investing in homes in Bend, Sunriver and Central Oregon. It is not legal, tax, lending, land use, rental licensing or inspection advice and does not predict prices, rental income or returns or promise results. Confirm financing with a lender, rental and land use rules with the city or county and any homeowners association, taxes with a tax professional, and property condition with a licensed home inspector. Helen Marston, Keller Williams Realty Central Oregon.
Written by